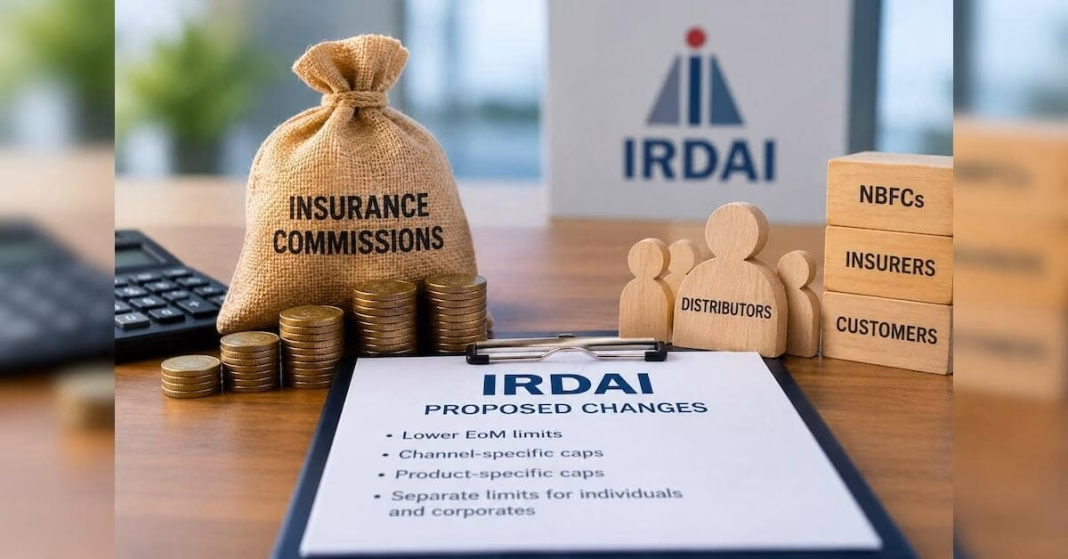

The proposals lower expense of management (EoM) limits for insurers and put product- and channel-specific caps on commissions. Individual and corporate distributors get separate limits, with higher caps for individuals to reflect the greater effort involved in sales.
Shriram Finance expects to lose around Rs 100 crore of the approximately Rs 350 crore it earned in insurance commissions last year. The company said that, relative to its balance sheet, the impact would not be material.
“For the size of our balance sheet, it is not material,” S Sunder, joint managing director and chief financial officer of Shriram Finance, said during the second-quarter earnings call.
Umesh Revankar, executive vice chairman, Shriram Finance, flagged a wider risk. A significant drop in distributor income could slow insurance growth, he said, as distributors play an important role in reaching customers. He expects the regulator to weigh stakeholder representations before finalising the framework.
Mahindra & Mahindra Financial Services (Mahindra Finance) also expects its fee income to take a hit if the draft goes through as proposed. It distributes insurance through Mahindra Insurance Brokers and its corporate agency business.
“If it comes as is, there will be a shave-off in our fee income,” Raul Rebello, managing director (MD) and chief executive officer (CEO), Mahindra Finance said during the earnings call.
He said the company was hopeful that stakeholder engagement would lead to further consideration of the proposals before the final framework is issued. Mahindra Finance is still scaling up insurance distribution through its branches, he added, which could build revenue over time.
Piramal Finance has put a number on the damage. If the consultation paper is implemented as proposed from April 1, 2027, the gross reduction in insurance commissions could weigh on its return on assets by 18-24 basis points in FY28.
Jairam Sridharan, MD& CEO, Piramal Finance, said improved economics at Pramerica Life Insurance, in which Piramal Finance has a 50 per cent stake, would offset part of the hit through consolidation. The company is also considering rationalising sales incentives and other product-related costs to cushion profitability.
The industry is also making representations to the regulator and expects Irdai to consider them before it issues the final guidelines. The eventual impact on lenders and other intermediaries will depend on those guidelines.