
The Confederation of Indian Industry (CII) has termed the Goods and Services Tax (GST) Council’s decisions on decriminalisation and rationalisation of enforcement powers among the most significant institutional reforms in India’s transition towards trust-based economic governance.
In an assessment of the decisions taken at the Council’s meeting on October 8, CII said their importance extends well beyond taxation. The decisions demonstrate how the Centre and states can work together on difficult reforms involving enforcement powers, revenue protection and taxpayer rights, it added.
The key measures include the proposed removal of arrest powers through the omission of Section 69 of the CGST Act, a fivefold increase in the monetary threshold for prosecution from ₹1 crore to ₹5 crore, narrowing of specified offences under Section 132, and rationalisation of imprisonment provisions with greater judicial discretion in sentencing. These require legislative amendments and are targeted for implementation from April 1, 2027. Criminal prosecution is retained for serious cases of deliberate fraud and evasion.
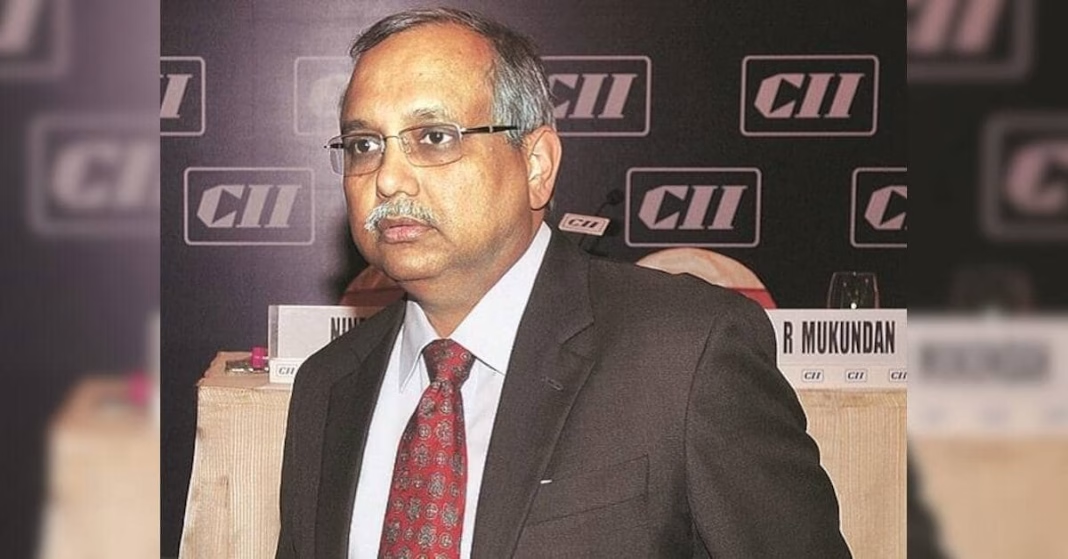
Chandrajit Banerjee, Director General, CII, said the decisions “deserve special recognition as a landmark institutional reform”. He appreciated the leadership of Prime Minister Narendra Modi and Finance Minister Nirmala Sitharaman, and the constructive role of state governments in achieving consensus.
“The importance of this reform is not simply that certain enforcement powers are being withdrawn. It is that the GST Council has recognised that effective tax administration need not depend on the threat of criminal sanctions,” Banerjee said. “This is one of the most consequential steps towards trust-based governance in recent years, particularly given the reach of GST across virtually every sector of the economy.”
The Central Board of Indirect Taxes and Customs (CBIC) issued a series of circulars on October 26 addressing practical concerns related to registration, notices and adjudication. These include the need to substantiate allegations of fraud with evidence, greater clarity in tax notices and reasoned adjudication orders. The circulars also seek to reduce unnecessary queries during registration and promote pre-show-cause notice intimation where feasible. Separately, CBIC on October 30 issued an instruction directing its field formations that no further arrests should be carried out under GST as an interim trade-facilitation measure, pending the legislative amendment to omit Section 69. The instruction also rationalises e-way bill interception procedures and sets a ₹10,000 threshold for issuing show-cause notices under Sections 73, 74 and 74A.
CII said the GST Council’s consensus-driven approach offers a model for India’s next generation of economic reforms, particularly in areas requiring Centre-state coordination such as land use, construction permissions, labour administration, utility connections, logistics and local regulatory approvals.
“India’s next phase of economic transformation will depend increasingly on cooperative federalism. Many of the remaining barriers to investment, manufacturing and enterprise growth lie at the intersection of Central, State and local regulations,” Banerjee observed.
CII also noted that the shift towards trust-based governance places a corresponding responsibility on industry to strengthen voluntary compliance, internal controls, documentation and responsible tax conduct. The confederation said it would continue working with its membership, particularly micro, small and medium enterprises (MSMEs), to promote better compliance practices.
“Ultimately, the strength of a regulatory system lies not in the severity of the powers it possesses, but in the compliance it secures, the fairness with which it operates and the confidence it inspires,” Banerjee said.
The measures are expected to reduce uncertainty, reputational risks, legal costs and management disruption for businesses, especially MSMEs and first-generation entrepreneurs, while retaining strong safeguards against deliberate fraud. Their full impact, CII noted, will depend on consistent implementation across jurisdictions.