Tuesday, November 17, 2026
8 C
London

Brainbees Solutions Shares snaps 3-day losing run, jumps 13%; JM Fin says worst over post Q2 | Markets News

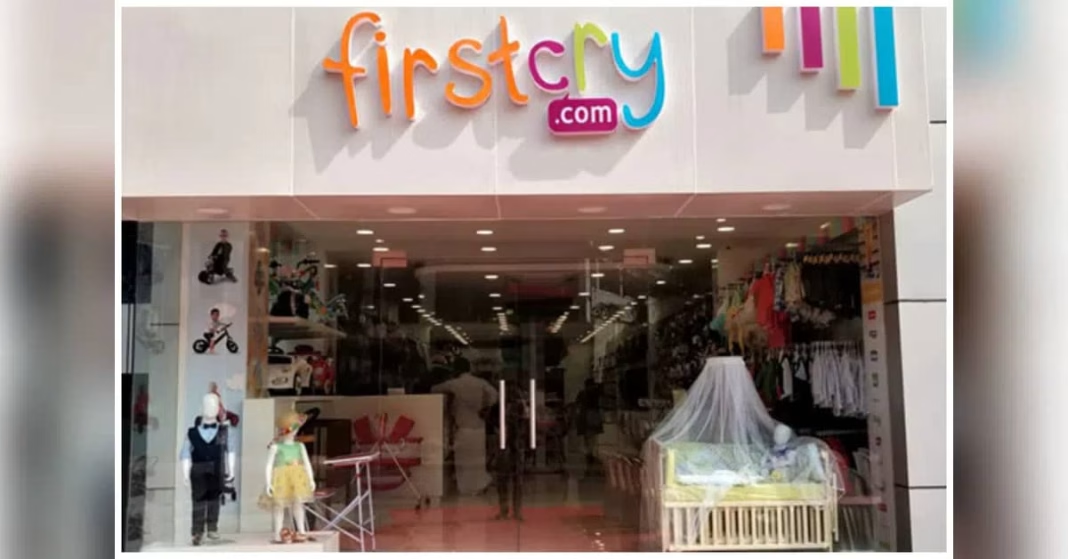
Firstcry-parent Brainbees Solutions’ stock rallied 13 per cent in Tuesday’s trading session, in line with the sharp surge seen in the benchmark indices, and snapped their three-day losing run. Higher than usual volumes also accompanied today’s move.


Firstcry’s stock gained 12.7 per cent to the day’s peak of ₹178.70 on the NSE. At last check, it was up 10.7 per cent at ₹175.67. According to data, Brainbees Solutions was among the top three volume gainers on the NSE, with 42.36 million shares having changed hands as of 11.30 am.


Despite today’s rise, Brainbees remains sharply lower this year, having lost 39 per cent on a year-to-date (YTD) basis and 47 per cent in one year. The stock had listed on the bourses on August 13, 2024, and has lost 61.5 per cent from its issue price of ₹465 based on day’s high.


Brainbees Solutions Q2 results

The company recently announced a mixed set of earnings for the second quarter of the financial year 2026-27 (Q2 FY27), wherein it posted a 14.1 per cent year-on-year (YoY) revenue growth to ₹2,395.8 crore.


Losses also narrowed from ₹50.5 crore in Q2 FY26 to ₹12.6 crore in Q2 FY27.


Although GMV growth of 9 per cent was partially impacted by festive demand shifting into Q3 FY27. Further, gross margin pressures, down 310bps YoY, due to residual diaper discounting and crude-linked cost pressures led to adjusted Ebitda margin decline of 220 bps YoY to 6.9 per cent, noted JM Financial analysts.


Management indicated that diapering intensity has moderated from Q2FY27 while online/offline gross margin has already recovered ~100 bps versus Q3 FY26 and should improve further through Q3/Q4FY27. 


JM Financial on Brainbees stock

Following the Q2FY27 gross margin miss, JM Financial said it has cut FY27E adjusted Ebitda by ~18 per cent, while broadly maintaining FY28–29E estimates as “worst is likely behind”. It expects diaper discounting to moderate, crude-linked pressures to ease, and price pass-throughs to catch up.


Adjusted PAT estimates are revised down ~62 per cent/~12 per cent/~11 per cent over FY27–29E, with the sharp FY27 change reflecting a low base and higher capex towards offline stores, said the brokerage. It revised the September 2027 target price to ₹245 (earlier ₹255) and maintained ‘BUY’. 


Disclaimer: Views and outlook in this report belong to the brokerages and analysts cited. They do not reflect the views of Business Standard. Readers are advised to exercise discretion.

Source link

Hot this week

Centre raises export duty on diesel, aviation fuel; petrol unchanged | Economy & Policy News

The duty on petrol exports ​remained ‌at zero1...

Learning the language of machine learning | MIT News

Ultimately, he and his group want to help people...

Capital Markets: Derivatives surge on volatility; cash, MF flows stay muted | Markets News

Disclaimer: This article is written by Motilal Oswal Wealth...

Nigeria Moves to Safeguard Detty December Tourism as Lagos Warns of Booking Fraud

Image generated with AiNigeria’s Lagos State has warned visitors...

Topics

spot_img

Related Articles

Popular Categories

spot_imgspot_img