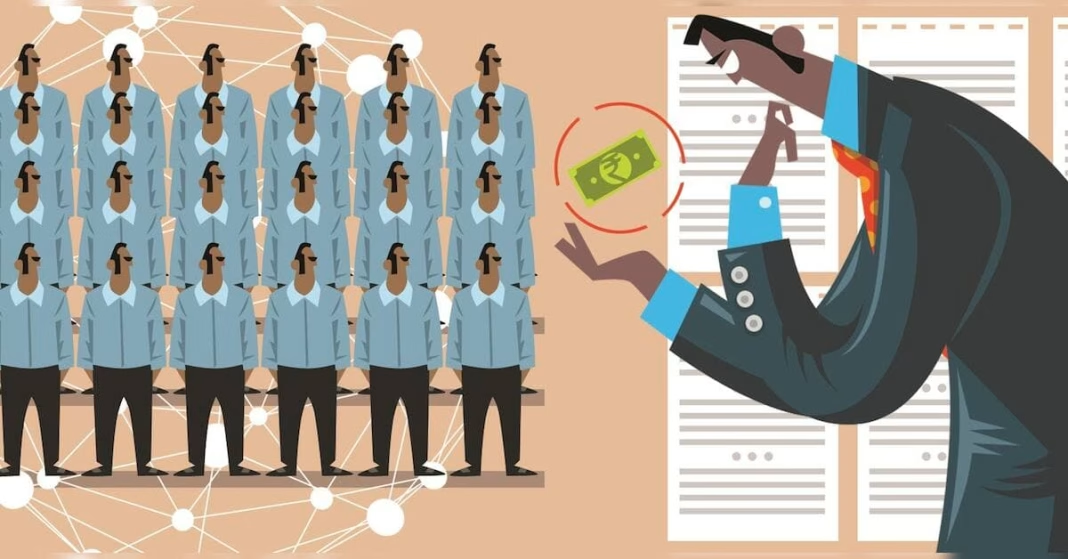

“Field data consistently points to a model where commissions are not viable, working-day footfall is volatile, and the agent’s monthly take-home in some areas frequently slips below what a MGNREGA wage would yield,” says Dharanidhar Tripathy, chief executive officer of the Business Correspondent Resource Council (BCRC). The average monthly payout is around ₹7,500 (down from around ₹10,000 a few years ago), even as field strength has fallen by nearly 400,000.
The Reserve Bank of India’s (RBI’s) “Draft (Branch Authorisation) Amendment Directions, 2026” (released on April 6 this year) folded the old business facilitator category into a clean two-tier classification of BC-banking outlets (BC-BOs) and BC-banking touchpoints. It brought long-overdue uniformity to the BC ecosystem on the payment of commission and remuneration.
Most consequentially, it explicitly contemplates that BC-BOs shall receive both fixed and variable compensation, with the IBA standing committee tasked to prescribe fixed monthly remuneration, benchmarked to an external indicator.
“Nearly two decades after it was rolled out, it is time that the BC network is aligned to the times. Financial inclusion has to be reimagined — be it remuneration or the technology,” says V S Das, former executive director, RBI. The first signs that this model is ripe for overhaul were evident in 2023 when the BCRC sought the setting up of an India Business Correspondent Equity Fund (akin to the India Microfinance Equity Fund) from the Finance Ministry’s Department of Financial Services. Both requests were a lift-off from the C Rangarajan Committee report on Financial Inclusion (January 2008), which called for funds to be provided to specialised institutions that offer capacity-building inputs to BCs.
Another pain point that BC firms may face shortly is that many of them have to evolve. The next wave of financial inclusion will not be about opening more bank accounts alone. It will be about helping people regularly use banking services to improve their financial well-being. To take financial inclusion to the next level, BCs need to do much more than facilitate basic transactions. “They can help people access savings products, credit, insurance, pension schemes and digital banking services. However, for the network to remain strong and sustainable, it is important that remuneration structures are reviewed to reflect the growing responsibilities of BCs,” says Shikhar Aggarwal, chairman of BLS E-Services, a technology-enabled digital service provider. A viable business model will encourage more entrepreneurs to participate and continue serving communities effectively. “It requires collaboration between banks, regulators and service providers, along with greater financial awareness and digital literacy among customers.”
Ajeet Kumar Singh, managing director and cofounder of SAVE Group, feels a BC network can provide a strong foundation but distribution reach alone does not make it a lending engine. “The real advantage lies in the customer proximity, local market understanding, and relationships that such a network develops over time. The challenge is to translate these strengths into responsible credit delivery, supported by the right technology, underwriting capabilities, and risk management systems.”
This has to be read along with law enforcement agencies freezing the accounts of BCs as the channel is allegedly being used by cybercriminals. This is again in the spotlight with the Digital Personal Data Protection Act, 2023, which comes into full effect from May 13, 2027. Regulated entities (REs) also need to establish a data governance framework and align it with their risk management framework. REs’ boards are to oversee this and review the reports and metrics annually or more frequently. On partnerships, the draft said REs should assess and put in place controls to mitigate data-related risks arising from third-party arrangements.
The business correspondent network is waiting for relief.