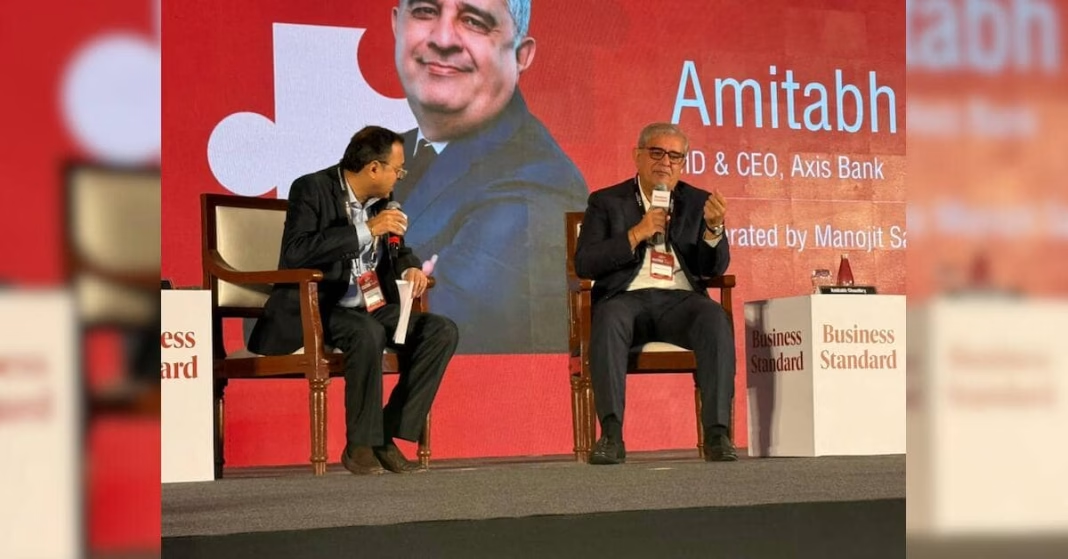

“There is never a dull day in India, and the same principle applies in banking as well,” Chaudhry said in a conversation with Business Standard’s Manojit Saha, highlighting the need for banks to balance growth and profitability with prudent risk management.
Expectations of interest rate hikes, rising inflation, and geopolitical uncertainties linked to the conflict in West Asia could add to the pressure on lenders, he said.
According to Chaudhry, higher deposit rates could increase banks’ funding costs, while rising borrowing costs could affect credit demand and repayment capacity. He cautioned that lenders would need to be selective about where they deploy capital as financial conditions tighten.
“Managing risk is the biggest skill in the banking system,” he said, stressing the need to balance growth ambitions with emerging vulnerabilities.
Credit growth may slow
Chaudhry expects credit growth to ease in the second half as the favourable base effect from the first half fades. However, he believes several structural factors will continue to support lending across the economy.
Longer working capital cycles, higher inventory requirements, and increased costs of purchasing goods are raising businesses’ financing needs. Infrastructure investment and demand for project finance could provide further support, while the expansion of banking services into underserved areas offers scope for additional lending.
He also pointed to the role of non-banking financial companies (NBFCs) in supporting credit expansion, alongside the availability of more customer data and improvements in banks’ ability to assess borrowers.
However, he cautioned that higher interest rates could temporarily weigh on overall credit growth.
Banks better placed to weather stress
Despite strong credit expansion, Chaudhry believes the Indian banking system is better placed to withstand asset quality stress than it was during the previous high-growth lending cycle, which was followed by a sharp rise in non-performing assets.
He identified stronger capital positions, higher provision coverage ratios, and improved underwriting practices as key differences.
Capital levels are around 500 basis points higher than during the earlier cycle, he said, while provision coverage ratios have risen from around 40-45 per cent to 70-75 per cent at most banks.
Greater information-sharing and improved monitoring have also made it harder for lenders to delay recognising deteriorating loans. The expected introduction of new expected credit loss (ECL) norms from April would further strengthen this approach, he said.
Retail and wholesale lending outlook
Chaudhry said banks should avoid viewing retail and wholesale lending as competing priorities, as both serve important functions in the economy.
Wholesale banking offers opportunities beyond corporate loans, including transaction banking, foreign exchange, and cash management. Small and medium enterprises are also important to economic growth and require financing to expand their operations.
Meanwhile, retail lending has benefited from the formalisation of the economy, stronger credit bureaus, greater availability of customer data, and the expansion of bank branches into smaller towns.
He expects retail lending to grow faster than wholesale lending over the next 18-24 months, provided risks remain manageable. However, he stressed that deposit mobilisation would be essential to supporting further expansion.
Talent and investment in banking
Chaudhry said attrition in banking largely reflected competition for talent within the financial services sector, with banks and NBFCs competing for experienced professionals as they expand into new markets and businesses.
He emphasised the need for lenders to build leadership pipelines, invest in mentorship, and prepare internal candidates for senior positions, while recognising that external hiring would sometimes be necessary.
On foreign investment, he said interest from overseas institutions reflected the opportunities in Indian banking, but capital alone would not guarantee success.
On the proposed insurance distribution norms, Chaudhry said the Insurance Regulatory and Development Authority of India (IRDAI) consultation paper was still at an early stage and banks would assess the final regulations before deciding how to respond. He said lenders could change the products they distribute or the customer segments they target depending on the final rules.