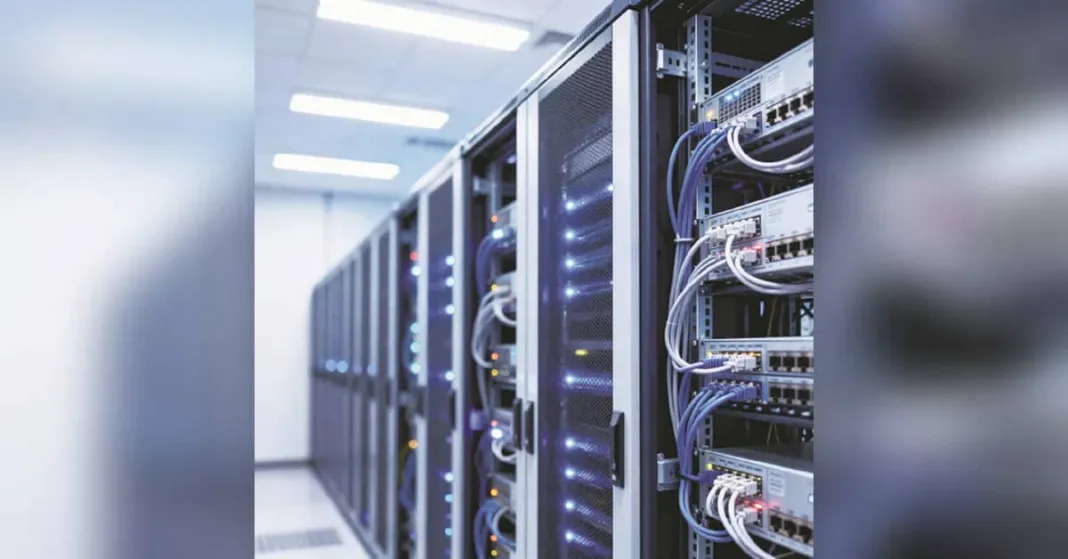

The commercial mortgage-backed securities (CMBS) market, long a mainstay of financing for America’s offices, apartments and malls, is being reshaped by a surge in data-centre deals, forcing investors to grapple with an entirely new set of risks.
From power availability and grid constraints to rapidly evolving requirements for cooling and computing density, CMBS buyers have been pushed into areas of underwriting that have historically had little to do with commercial real estate. Even familiar questions about tenant demand and stability are changing as facilities depend on a handful of often-secretive hyperscalers whose future needs can be difficult to gauge. If those tenants leave when their leases expire in the coming years, highly specialised buildings could be costly to repurpose.
About $17 billion of data-centre CMBS has been issued since the start of 2025 — more than triple the amount sold over the previous two years. During that period, data centres have grown to account for roughly 8 per cent of new commercial property bond deals. With billions more in the pipeline, industry veterans are rapidly revamping their risk-assessment playbooks to try to steer clear of any potential blow-ups that could leave a hole in their portfolios.
Many of the risks CMBS buyers have long had to weigh still apply, but the factors shaping them look very different when it comes to data centres. Take the lease agreements themselves. Provisions covering power costs, minimum capacity commitments and downtime determine who absorbs unexpected expenses, which can reduce the cash available for servicing debt. Scrutinising those terms can also be more difficult, with tenants often insisting that their identities and other lease details be kept confidential.
“Traditional CRE investors know how to underwrite offices, apartments, warehouses and retail because leases tend to be relatively standardised and tenant information is reasonably transparent,” said Ben Hunsaker, a portfolio manager at Beach Point Capital Management. “Data centres are much more opaque.”
Location is another example. Instead of judging properties based on how close they are to transportation, amenities or a city’s core, prime sites are now the ones with access to cheap electricity and available transmission capacity. Those advantages can determine how competitive facilities remain and what they are worth when loans mature.
Tenant concentration and lease rollover risk have also changed. In an office or apartment, re-leasing risk is often a simple matter of finding another client. When it comes to data centres, however, just as critical is whether bespoke electrical and cooling setups can even accommodate other firms and what the ultimate price tag would be to overhaul a facility if they cannot.
For CMBS investors, that raises the prospect of higher capital spending, longer periods without rental income and weaker recoveries if a borrower runs into trouble. Then there are considerations that are almost entirely new for CMBS buyers.
The rapid evolution of artificial intelligence chips can drive sharply higher power and cooling requirements. A facility designed around one generation of hardware could, therefore, become outdated in just a few years, reducing its value and making its debt harder to refinance.
The industry is also confronting a level of opposition that is rarely seen elsewhere in commercial real estate, turning data centres into a major political issue at both the local and national levels. Concerns over utility costs and the strain on local infrastructure have fuelled calls to restrict new developments in some communities, making the future regulatory environment particularly hard to predict, market watchers say.