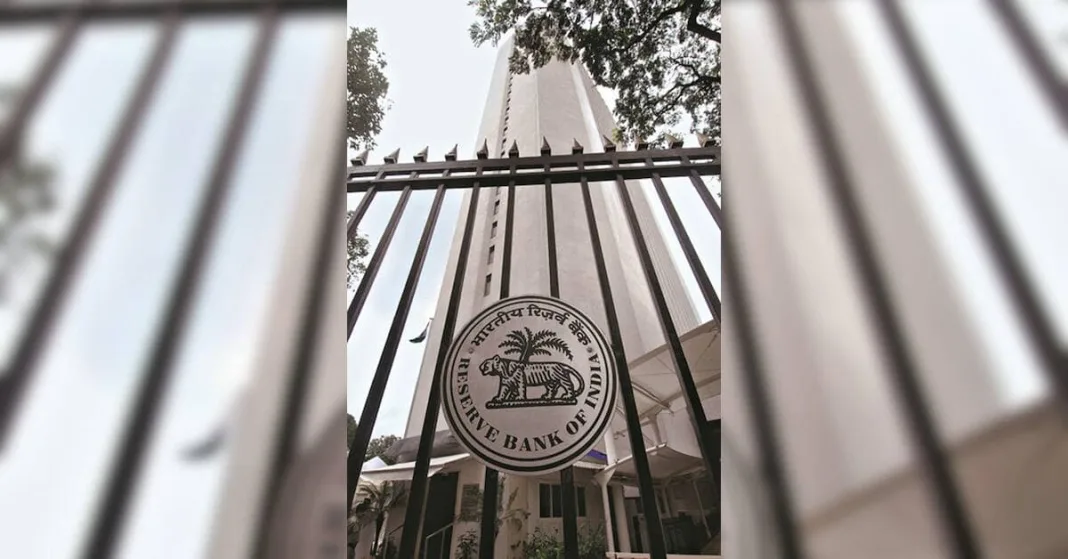

With the Reserve Bank of India’s (RBI’s) recent rate increase already priced in by markets, the move has had little impact on bond yields or the rupee, and the central bank may need to consider other measures, including an asymmetric widening of the liquidity adjustment facility (LAF) corridor, to stabilise markets amid global uncertainty, according to a State Bank of India (SBI) report.
“Amidst the other measures suggested, we understand the asymmetric widening of the corridor could be the most effective (as tested in the past times of turbulence in 2013/2020/2022) which the Central Bank has exclusive authority of, by dint of regulatory prescriptions. While amendment in RBI act (Section 45ZB) entails the MPC to determine the policy rate (i.e. Repo rate) required to achieve the inflation target, the day to day liquidity management function is solely in the domain of RBI, an asymmetric LAF corridor in exceptional times enshrined in its very purpose,” the report said.
The report said widening the corridor could be more effective than waiting for the next rate action, as the RBI has the authority to manage liquidity independently of the Monetary Policy Committee’s (MPC’s) decisions on the policy rate.
During the Covid-19 pandemic, the central bank had widened the corridor from 50 basis points (bps) to 65 bps on March 27, 2020, by lowering the reverse repo rate while keeping the marginal standing facility (MSF) rate at its usual spread over the repo rate. On April 17, it cut the reverse repo rate further, taking the corridor to 90 bps. In July 2013, it had widened the corridor to 400 bps in response to the taper tantrum.
The report also said the situation warrants an “agile and tactile” rate response, which could include a jumbo increase of 50 bps “sooner than later”. This implies not waiting for the next MPC meeting, and an off-cycle policy or a wider corridor looks like a “sine qua non”, it said. While the market consensus is for a shallow rate-increase cycle, the report said it continues to believe in a larger increase at the December policy meeting, as growth will remain strong and top 7.5 per cent again.
On the exchange rate, the report said the narrative has shifted towards managing the currency as much as inflation expectations, with the dollar index gaining momentum on expectations of further Fed rate increases and strong US growth.
Non-deliverable forward (NDF) markets reflect the stress, with the short end of the curve spiking and the annualised cost at times double that of the longer end, with action concentrated in the one-to-three-month tenor. The one-year NDF premium peaked at 4.02 per cent on October 8, while the three-month and one-month premiums hit 1.40 per cent and 0.67 per cent, respectively.
The report suggested tightening the time allowed for exporters to bring in proceeds. The current period, say 15 months, could be cut to six months as a norm, with extensions on a case-by-case basis, it said. It added that any undue delay should attract some punitive deterrence mechanism.
The report also said the government needs to support the RBI by enhancing flows of patient capital in debt and equities by tweaking the tax and capital gains structure.
Citing the RBI governor’s recent Princeton address, the report said a good central bank should be systematic enough to preserve credibility, flexible enough to adapt, and transparent enough that uncertainty about the economy does not become uncertainty about the central bank itself.